Real Estate Loan Due Diligence: What Lenders Must Verify
Before a loan funds, a lender has to prove the borrower can repay and the collateral is what it seems. Here is what real estate loan due diligence must verify.
Scalance Global
On this page
- Key Takeaways
- Why Real Estate Loan Due Diligence Matters
- Verify the Borrower's Ability to Repay
- Verify the Property and Its Value
- Verify Identity and Watch for Fraud
- Verify Compliance and Disclosures
- Business Purpose and Investor Loans
- Building a Loan File That Holds Up Later
- Frequently Asked Questions
- Conclusion
Real estate loan due diligence is the work a lender does before funding to prove two things: the borrower can repay, and the property can secure the debt. Lenders must verify income, employment and assets with third-party records, confirm debts and credit history, test the payment against the borrower's budget, and validate the property's value, condition, title, flood status and insurance. They also have to confirm who the borrower really is, check the loan against the disclosure and fair lending rules that apply, and keep evidence of every step in a file that survives a later audit or sale.
Key Takeaways
Underwriting decisions are only as good as the evidence behind them. These are the points a lender cannot skip.
For most consumer mortgages, federal rules require a good faith ability to repay determination based on eight factors, verified with reasonably reliable third-party records.
Income, employment and assets are checked against the source, not just the application.
The property is verified separately from the borrower: value, condition, title, lien position, flood zone and insurance.
Identity, sanctions and fraud checks protect the lender from lending to the wrong person or on a fake transaction.
Business purpose and investor loans follow different rules, but the same verification habits still protect the lender.
The loan file has to show the work, because investors, auditors and regulators review the file, not the underwriter's memory.
The sections below follow the order most loan files are built, from borrower to collateral to compliance. Rules vary by loan type, investor and state, so treat this as a framework rather than a full policy manual.
Why Real Estate Loan Due Diligence Matters
A loan that looks fine at closing can turn into a problem months later. Income that was never verified, a missed judgment lien or a flood zone nobody checked can lead to a default, a loss on the collateral, a buyback demand from an investor or a regulatory finding. Due diligence is how a lender keeps those surprises out of the portfolio.
There is also a capital markets reason. Most loans are sold, pledged or securitized at some point, and every buyer down the line will check the file. Missing documents or unresolved issues can make that process more difficult. At Scalance, we understand how important a well-prepared loan file is, not just at origination but throughout its lifecycle. Our secondary market support services help lenders and financial institutions maintain the documentation and file quality needed for smoother loan reviews and transactions.
Verify the Borrower's Ability to Repay
For most closed-end consumer loans secured by a dwelling, the Consumer Financial Protection Bureau's ability to repay rule sets the floor. Under 12 CFR 1026.43, a creditor must make a reasonable, good faith determination that the consumer can repay, and it must consider eight factors: current or reasonably expected income or assets, employment status, the monthly payment on the loan, payments on any simultaneous loan, mortgage-related obligations such as taxes and insurance, current debts including alimony and child support, the debt-to-income ratio or residual income, and credit history.
The rule does not just ask lenders to consider those factors. It asks them to verify the information they rely on with reasonably reliable third-party records. Employment status is one exception, since it can be verified orally as long as the lender documents what it learned. The Qualified Mortgage definitions offer a presumption of compliance, and since the 2020 revisions the General QM test is based on how the loan's price compares to the average prime offer rate rather than a fixed 43 percent debt-to-income cap. Lenders still have to consider and verify income and debts under that test.
Income and Employment
Salaried income is usually checked with pay stubs, W-2 forms and a written or verbal verification of employment. Many lenders also pull IRS tax transcripts to confirm that the returns in the file match what was filed. For loans sold to Fannie Mae, the Selling Guide expects a verbal verification of employment close to the note date, generally within 10 business days for salaried borrowers, so a job change in the final weeks before closing does not slip through.
Self-employed borrowers take more work. Underwriters review personal and business tax returns, profit and loss statements and business bank statements, then calculate qualifying income based on the trend rather than the best year. A business that earned less this year than last usually gets the lower figure.
Assets and Reserves
Assets cover the down payment, closing costs and any reserves the program requires. Bank and investment statements show the balance, but they also show where the money came from. Large deposits that do not match payroll need a paper trail, because an undisclosed loan dressed up as savings changes the borrower's debts. Gift funds need a gift letter and evidence of the transfer. A cash to close calculator helps confirm that verified funds actually cover what the borrower will owe at the table.
Debts, Credit and the Payment Itself
The credit report shows open accounts, payment history, inquiries and public records. Underwriters compare it with the application and ask about anything new, especially recent inquiries that might signal a car loan or credit line opened before closing. The monthly payment on the new loan has to be calculated correctly, including principal, interest, taxes, insurance and any association dues. Running the numbers through a mortgage calculator and an amortization schedule calculator is a simple way to catch errors in a payment quoted by a broker.
Verify the Property and Its Value
The borrower's file answers whether the loan will be repaid. The collateral file answers what happens if it is not. That means the property needs its own review, separate from the borrower.
Appraisal and Valuation
An appraisal or other approved valuation supports the loan-to-value ratio. Reviewers check that the comparable sales are truly comparable, that the subject's condition and features match the photos and the contract, and that adjustments are reasonable. Appraiser independence matters too: federal rules prohibit pressuring an appraiser to hit a number, and lenders generally must give consumers a copy of appraisals and written valuations for first-lien dwelling loans. A quick check with an LTV and ARV calculator shows whether the value and the loan amount still leave enough equity cushion.
Title, Liens and Vesting
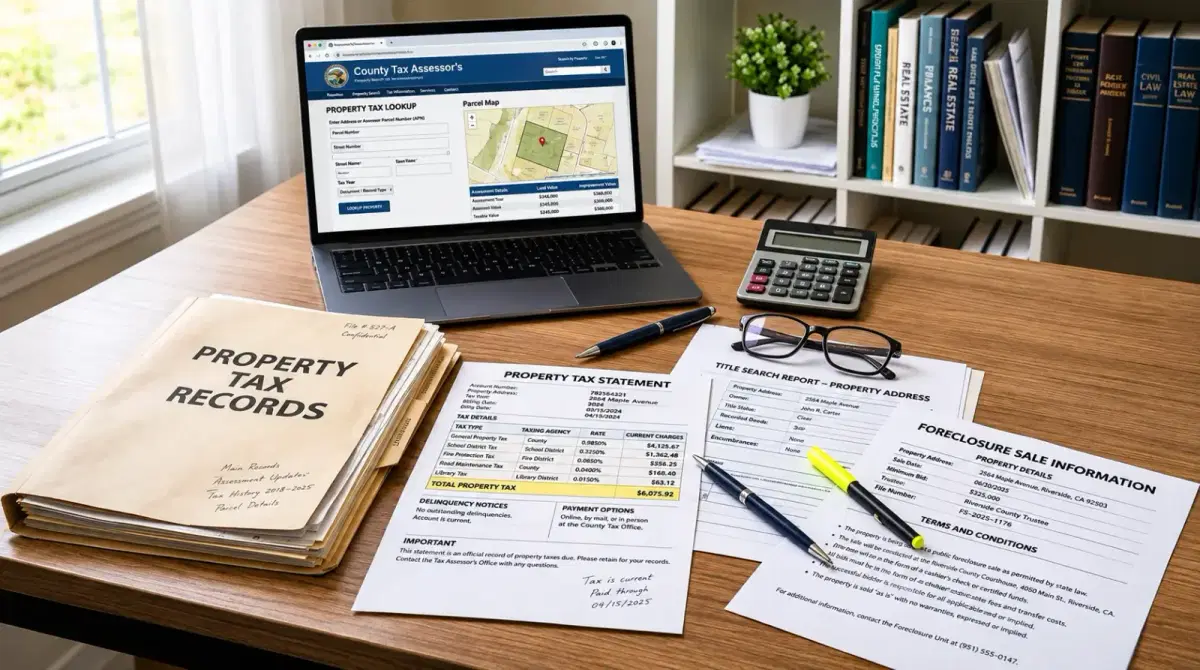
Title review confirms that the borrower or seller actually owns the property, that the lender's mortgage will sit in the expected lien position, and that taxes, judgments, mechanics' liens and prior mortgages are paid or subordinated. The vesting on title should match the names on the loan documents. Our guide on how to do a title search on a property in the US explains how these records are read, and lenders who need a consistent standard across markets often rely on outside title services.
Unpaid property taxes deserve their own line on the checklist, because tax liens generally outrank a mortgage. Property tax services can confirm the current status and any delinquent years before funding.
Flood Zone and Insurance
Lenders must determine whether a property sits in a special flood hazard area, and if it does and flood insurance is available, coverage is required for federally related loans. Hazard insurance should name the lender correctly as mortgagee, with coverage that meets the investor's requirements and an effective date on or before funding. Condominium loans add a review of the master policy and, depending on the investor, the project itself. The lender's title policy is part of the same insurance picture, and a title insurance calculator gives a quick estimate of what it should cost.
Verify Identity and Watch for Fraud
Lenders need to know who they are lending to. Identity checks compare government ID, Social Security number validation and the credit report's identity data with the application. Sanctions screening against the Treasury Department's OFAC lists applies to every party, including sellers and entities. Non-bank residential mortgage lenders and originators have also been required to keep anti-money laundering programs and file suspicious activity reports since FinCEN extended those rules to them in 2012.
Fraud reviews look for patterns rather than single facts. Common red flags include a recent quick resale at a much higher price, a seller who acquired the property days ago, occupancy claims that do not match the borrower's other addresses, and bank statements whose fonts or balances do not add up. Pre-funding checks catch many of these, which is why lenders that fund quickly lean on structured pre-funding diligence instead of a last-minute scan.
Verify Compliance and Disclosures
A loan can be well underwritten and still defective if the disclosures are wrong. Under the TILA-RESPA Integrated Disclosure rule, consumers generally must receive the Loan Estimate within three business days of application and the Closing Disclosure at least three business days before consummation, and certain changes restart that clock. Fee tolerances, the rate lock, high-cost and higher-priced loan tests, and state licensing for the originator all belong on the compliance review. A closing cost calculator gives a rough benchmark when a fee on the disclosure looks out of line.
Fair lending is part of this check as well. Consistent underwriting, documented exceptions and pricing that follows the rate sheet protect both borrowers and the lender. Regulation Z also requires creditors to keep evidence of ability to repay compliance for three years after consummation, so the documentation standard is not optional.
Business Purpose and Investor Loans
Loans to investors for rental or fix-and-flip properties, often made by private lenders, usually fall outside the consumer ability to repay rule. That does not make verification lighter. It shifts the focus toward the property's cash flow, the borrower's experience and the entity that will own the asset.
For a rental property, lenders look at the lease, the market rent and whether the income covers the debt. A rental yield calculator and a cap rate calculator give a quick read on whether the deal works.
For short-term bridge and rehab loans, the exit plan and the after-repair value matter most, and the hard money loan calculator and bridge loan calculator help test the numbers.
Entity borrowers need formation documents, proof of good standing, an operating agreement showing who can sign and personal guarantees where the program requires them. Rehab loans add a scope of work and a budget, and lenders that release funds in stages need inspection-based construction draw support so each draw matches completed work. Lenders who make these loans across several asset types can read more about private money lending support.
Building a Loan File That Holds Up Later
Due diligence does not end when the underwriter signs off. The final file should tie every condition to a document, show who cleared it and when, and include the executed note, security instrument, title policy, appraisal, disclosures and insurance. Missing trailing documents, such as the recorded mortgage or final title policy, are a common reason loans get kicked out of a sale later. Coordinated settlement services help make sure the closing package is complete before the file moves on.
Lenders that close high volumes often use closing and post-funding support to chase those items, and automation can help flag missing pieces early. Our post on real estate technology automating title operations looks at how lenders are using it.
If a loan will eventually be securitized, it helps to know what securitization and capital markets support reviewers will look for, because they will compare your data to your documents line by line.
Frequently Asked Questions
Can a lender rely on the appraisal ordered by a previous lender?
Sometimes. Many programs allow an appraisal to be transferred from another lender if it meets independence and age rules, but the new lender remains responsible for reviewing it. Investors set their own limits, so check the guide before accepting one.
Does due diligence change when the borrower is refinancing rather than buying?
The core checks stay the same, but the focus shifts. A refinance adds a payoff statement for the existing loan, a review of the current lien position and, for cash-out loans, a closer look at why the borrower needs the cash.
Who pays for third-party verifications?
It depends on the lender and the program. Some fees, such as the appraisal and credit report, are commonly passed to the borrower and disclosed on the Loan Estimate, while others are absorbed by the lender as part of its cost to originate.
How long should a lender keep the loan file?
At a minimum, as long as the regulations and the investor require. Some records have three-year retention rules, while state law, investor contracts and litigation holds can require much longer.
Conclusion
Real estate loan due diligence comes down to proving the borrower can repay and the property can secure the debt, then keeping evidence of both. Verify income, assets and debts with third-party records, review the property's value, title, taxes, flood status and insurance on its own terms, screen every party for identity and fraud risk, and confirm the disclosures were right. Do it consistently, document it fully, and the loan will be easier to hold, sell or defend later. Lenders who want a second set of eyes on title and collateral before closing can start with ancillary services built around their workflow.
This article is for general information only and is not legal, compliance or financial advice. Lending rules vary by loan type, investor and state, so consult qualified counsel or a compliance professional about your specific program.
Want this handled for you?
Title & settlement, investor diligence, private money lending and automation technology — run by one operational partner. Tell us where your pipeline is stalling.
Talk to Scalance