Pre-Funding Diligence
Pre-Funding Diligence: Know the Collateral Before You Fund
A fast loan still needs a clear collateral record. Before the wire goes out, the lender needs to know what property is being financed, what is already recorded against it, what exposure sits with the borrower or entity, and which closing conditions remain open.
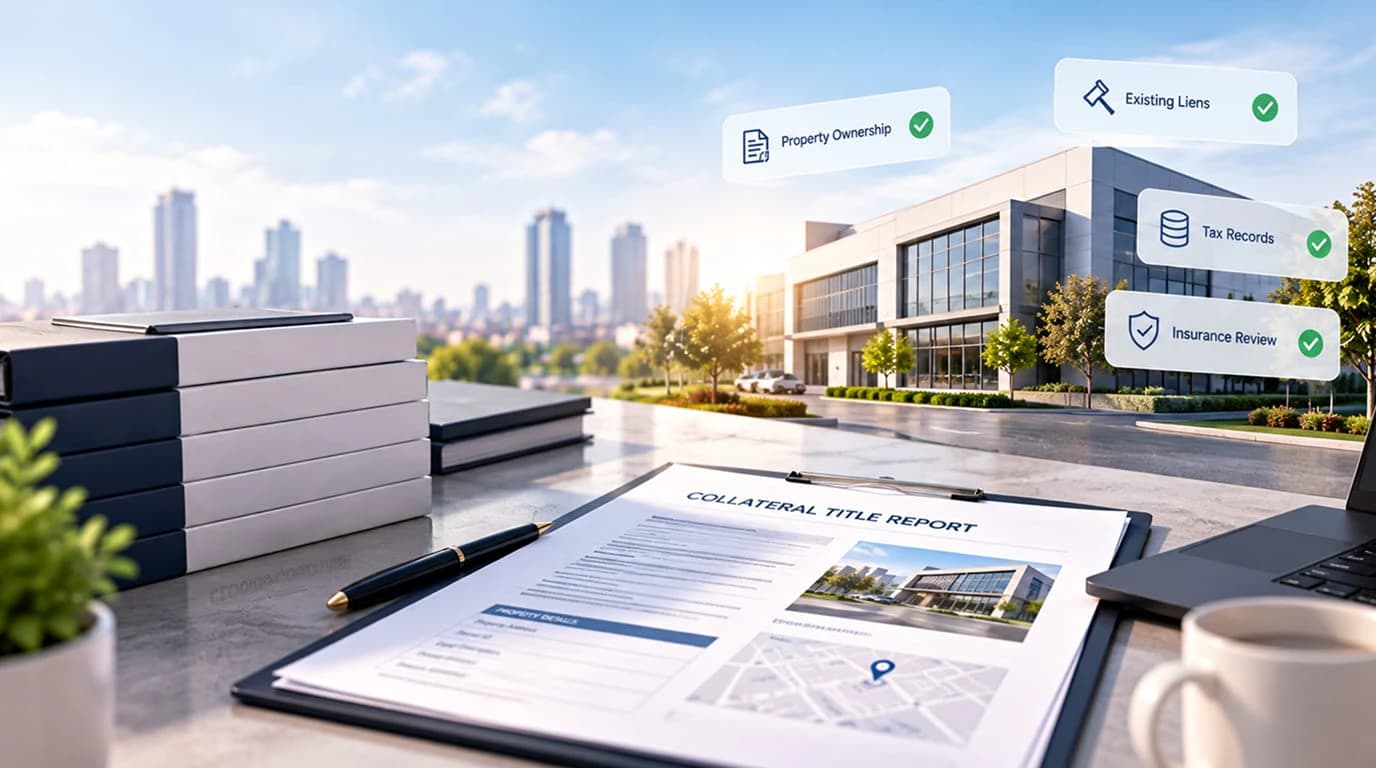
Scalance provides pre-funding collateral title reports for private and hard money lenders, with borrower and entity lien and judgment sweeps, title commitment exception review, legal description and parcel matching, existing lien payoff verification, tax, municipal and HOA charge review, insurance checklist review and closing-condition tracking. Scalance states a 24–48 hour SLA for the pre-funding collateral report.
Why Pre-Funding Diligence Matters
The most useful time to find a collateral problem is before the lender funds it.
A property can have an unresolved lien. A borrowing entity can carry a judgment. An existing payoff can still be open. A legal description can fail to match the parcel being relied upon. A title commitment can contain an exception that changes what needs to be resolved before closing.
Pre-funding diligence brings those questions into the deal while the lender can still act on them.
Pre-Funding Collateral Title Report
The collateral title report is the starting point for the lender's review. Scalance's workflow provides a rapid pre-funding collateral title report and supports it with source documents, outstanding conditions and a follow-up tracker.
The point is not to create another report for the file. It is to give the lending team a record-based view of the collateral before the funding decision is made.
Title Commitment Exception Review
A title commitment can contain exceptions, requirements and conditions that need attention before funding. Scalance reviews title commitment exceptions within the agreed scope and surfaces the items that need follow-up.
The lender can then decide which conditions must be cleared, escalated or accepted within its own underwriting and closing process.
Legal Description & Parcel Matching
The street address is only one identifier. The legal description and parcel need to match the collateral the lender believes it is financing.
Scalance includes legal-description and parcel matching in the pre-funding scope.
Borrower, Guarantor & Entity Lien and Judgment Searches
The collateral search should not stop at the parcel.
Scalance's service searches the borrower, guarantor and LLC for liens and judgments alongside the property review. That matters because a property-only search cannot reveal entity-level exposure attached to the people or companies behind the transaction.
The findings support the lender's underwriting and closing process. Scalance does not make the lending decision.
Existing Lien Payoff Verification
An existing lien that is supposed to be paid at closing should be treated as a tracked condition, not an assumption.
Scalance includes existing lien payoff verification in the pre-funding workflow.
Tax, Municipal & HOA Charge Review
Property-related charges can become closing conditions or collateral concerns. Scalance includes tax, municipal and HOA charge review within the pre-funding scope.
Closing Condition Tracking
The final days before funding often involve several open conditions owned by different people. Scalance can maintain the follow-up tracker so the lender has a clearer view of outstanding conditions, responsible parties and supporting documents.
That gives the lending team one operational view of what remains before the wire goes out.
Nationwide Pre-Funding Searches and Unusual Collateral
Nationwide Pre-Funding Searches
Scalance's service states 50-state coverage and nationwide search with local recording nuance.
That matters for lenders working across multiple states because the same request can involve different recording practices and local public-record requirements.
Unusual Collateral Before Funding
The service includes:
- Land and unimproved collateral diligence
- Ownership and recorded-encumbrance research
- Access and easement identification
- Deed restriction research
How the Pre-Funding Workflow Works
01
Submit the Deal
Provide the property, borrower/entity information and agreed diligence scope.
02
Search the Record
Scalance researches the collateral record and borrower/entity exposure within the defined scope.
03
Review Exceptions
Title exceptions, liens, judgments, payoff conditions and other findings are organized for lender review.
04
Track What Remains
Outstanding conditions are placed into a follow-up workflow with responsible parties.
05
Deliver Before Funding
The collateral findings report and supporting documents are delivered against the agreed SLA so the lender can make its own funding decision.
Onboarding Your Lending Desk
01
Kickoff & Lending-Scope Confirmation
Scalance finalizes states, collateral types and turnaround SLAs in one business day.
02
Pilot Run — 10 Files
A 10-file pilot with no setup fees and no long-term commitment.
03
Live Pre-Funding Flow
Approved files move through SLA-backed delivery, QC and secure delivery. The workflow can continue into post-funding recording confirmation when required.
Built for Private Lender Operations
This service is for lending teams that need the same diligence process repeated across transactions without building an internal research queue for every file.
It fits private lenders, hard money lenders, real estate lenders, bridge lenders and other teams funding against real estate collateral where title, lien and entity research has to keep pace with the transaction.
The commercial question is straightforward: can Scalance take the pre-funding research workload, run it against an agreed SLA and return findings that your lending team can actually use?